Share the process, preserve local requirements
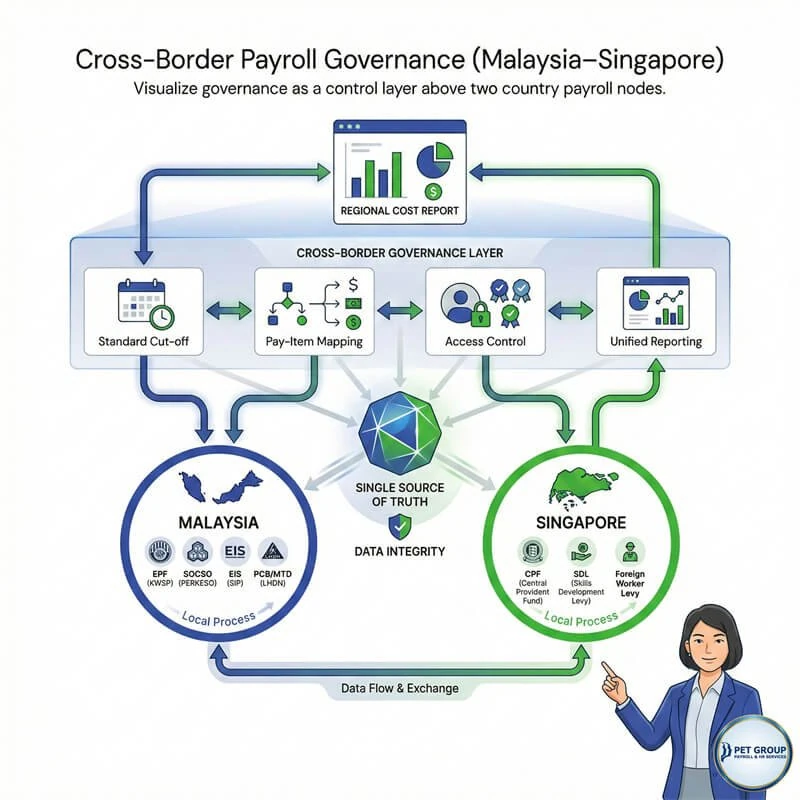
A regional team needs consistent information without treating Malaysia and Singapore as one statutory system. Align the input templates, review stages and reporting definitions while keeping employee classifications, local deductions, filings and payment responsibilities separate.
What to standardise across the group
- A shared calendar showing each entity’s input, review and approval dates.
- Named HR, Finance and payroll contacts, including backups.
- Stable employee and entity identifiers to prevent duplicate records.
- A pay-item dictionary explaining how each local item maps to group reports.
- Consistent cost-centre codes and headcount definitions.
- A reporting currency and documented exchange-rate convention.
A practical reporting model
Retain local payroll registers and statutory outputs in their original currency. Produce a separate group summary for management, with explained differences in period, currency or scope. A transfer between employing entities should be recorded as a controlled employee event, not simply an edit to a country field.
Set access according to role and entity. Group management may need aggregate costs without needing every employee’s bank or identification details. Agree cross-border data handling before transferring records.
Transition both entities deliberately
Inventory the current payrolls, compare field definitions and collect approved opening balances. Test representative employee changes and reconcile the results at entity level before reviewing the group total. Sign off each local payroll and then the consolidated reporting format.
Local service details
Questions employers ask
Does coordination remove local employer responsibilities?
No. Each employing entity retains its obligations and approval responsibilities. The service scope should define local processing, submission and payment roles.
Can we use one currency for reporting?
A group report can use an agreed reporting currency, while local payroll and payment records remain separately reconcilable. Document the conversion basis and period.