Reconcile before release
Compare the payroll register with the proposed bank file: employee count, payment totals and payment references should agree or have documented explanations. Match statutory totals to their supporting payroll items and map accounting outputs to the agreed ledger codes.
A successful file upload alone does not confirm that employees were paid. Payment rejection handling and bank confirmation need their own owner and follow-up process.
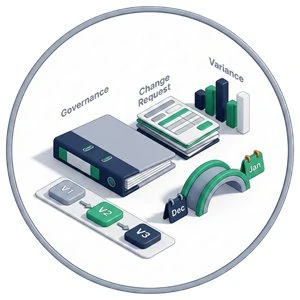
Make variances useful
- Headcount: reconcile opening staff, joiners, leavers and closing staff.
- Gross pay: explain salary revisions, incentives, arrears and unpaid leave.
- Variable pay: review unusual overtime, commissions or claims.
- Net pay: investigate unexpected zero, negative or large movements.
- Cost allocation: check department, outlet and project-code changes.
An agreed monthly reporting pack
| Output | Purpose |
|---|---|
| Payroll summary | Review gross pay, deductions, employer costs and net pay. |
| Variance report | Explain significant movements against a comparable period. |
| Cost-centre report | Allocate workforce costs to the agreed departments or projects. |
| Approval record | Connect the final version with the client’s authorisation. |
| Exception log | Track unresolved items, corrections and their owners. |
Regional reporting without mixing local rules
For Malaysia and Singapore entities, agree the reporting currency, exchange-rate convention, reporting period and cost definitions. Keep local statutory calculation separate from group-level presentation. A consolidated total is only useful when both entities use the same definitions.
Combine reporting with accounting data mapping or Malaysia–Singapore coordination.