Updated 22 September 2026 · PET Group
Prepare the annual records
- Reconcile employee-level annual totals to the final monthly payroll records.
- Confirm names, identifiers, employment dates and relevant employee changes.
- Review benefits, bonuses, allowances and adjustments against the reporting requirements.
- Identify records from a previous payroll provider when a migration occurred mid-year.
- Assign preparation, review, submission and employee-query responsibilities.
Malaysia: distinguish employee statements and employer reporting
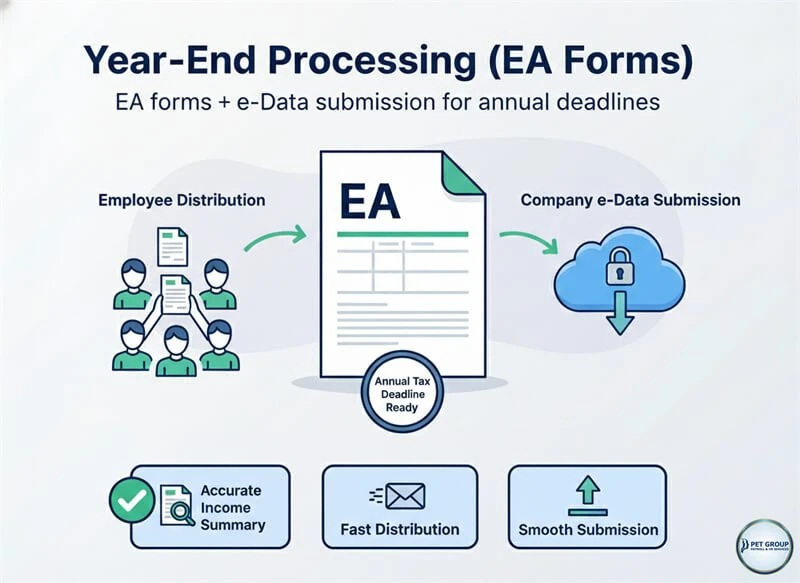
The EA statement and the employer’s Form E/CP8D reporting have different purposes. Reconcile the underlying employee data and confirm the current submission requirements and filing programme with HASiL. Do not treat issuing an employee statement as completion of every employer obligation.
Singapore: use current IRAS requirements
Check the IR8A-related information and applicable appendices against the reporting year and your AIS obligations. IRAS distinguishes current reporting from older-year forms; IR8S is described as applicable before YA 2026. Keep any historical correction work separate from the current year’s reporting.
A review trail that survives a correction
Keep a controlled final data set, evidence of review and submission acknowledgements. If a record needs correction, document what changed and whether the employee statement, authority submission or both need updating. Retain the original and revised versions according to the applicable retention requirements.
Official references
Check the current authority guidance when applying rules to an employee or payroll period. Sources reviewed on 22 September 2026.
Connect annual reporting to monthly reconciliation.